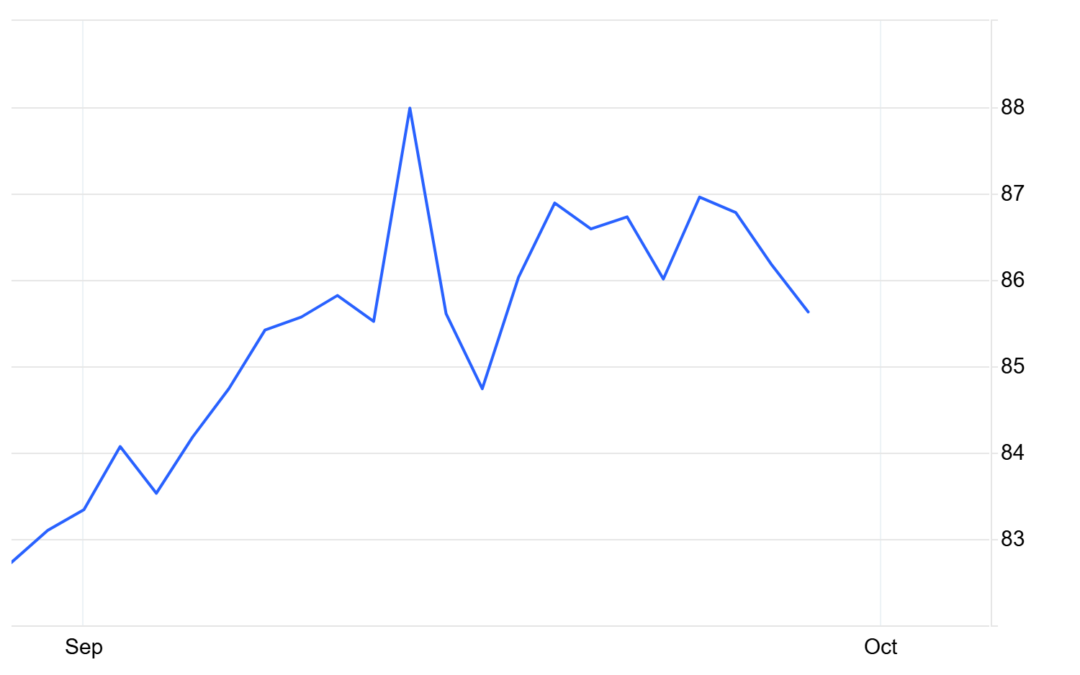
The EUA DEC26 contract spent the week of 21 to 25 September consolidating, trading between 85,38 and 87,75 €/ton and ending 0,13% lower. Early selling pressure met support around 85,50–86,00 €/ton, which held firmly on Thursday, a day after EU countries agreed to keep more spare permits in the ETS to curb price spikes. That Wednesday session also saw the week’s peak volume of 26,45 million allowances. Member states’ push to reintroduce a cap on allowances held in reserve reinforced the same theme of tighter price management.
Later, the market twice failed to break above 88,00 €/ton, and Friday’s test of 87,75 €/ton faded into a 86,78 €/ton close. Eurofer’s warning that steel carbon costs could quadruple by 2031 without slower free-allocation phase-out added to the debate on how far the ETS can tighten, while the ERCST review stressed that decarbonization depends on more than carbon prices. A break above 88,50 €/ton could open the way to 90,00 €/ton, while a drop below 85,50 €/ton risks a correction.